
Explore the latest IFRS 18 updates, key changes, 2027 effective date and preparation steps for UAE businesses with Jaxa Chartered Accountants.
The introduction of IFRS 18- Presentation and Disclosure in Financial Statement represents a new approach to presenting and disclosing financial reporting that will replace IAS 1- Presentation of Financial Statements.
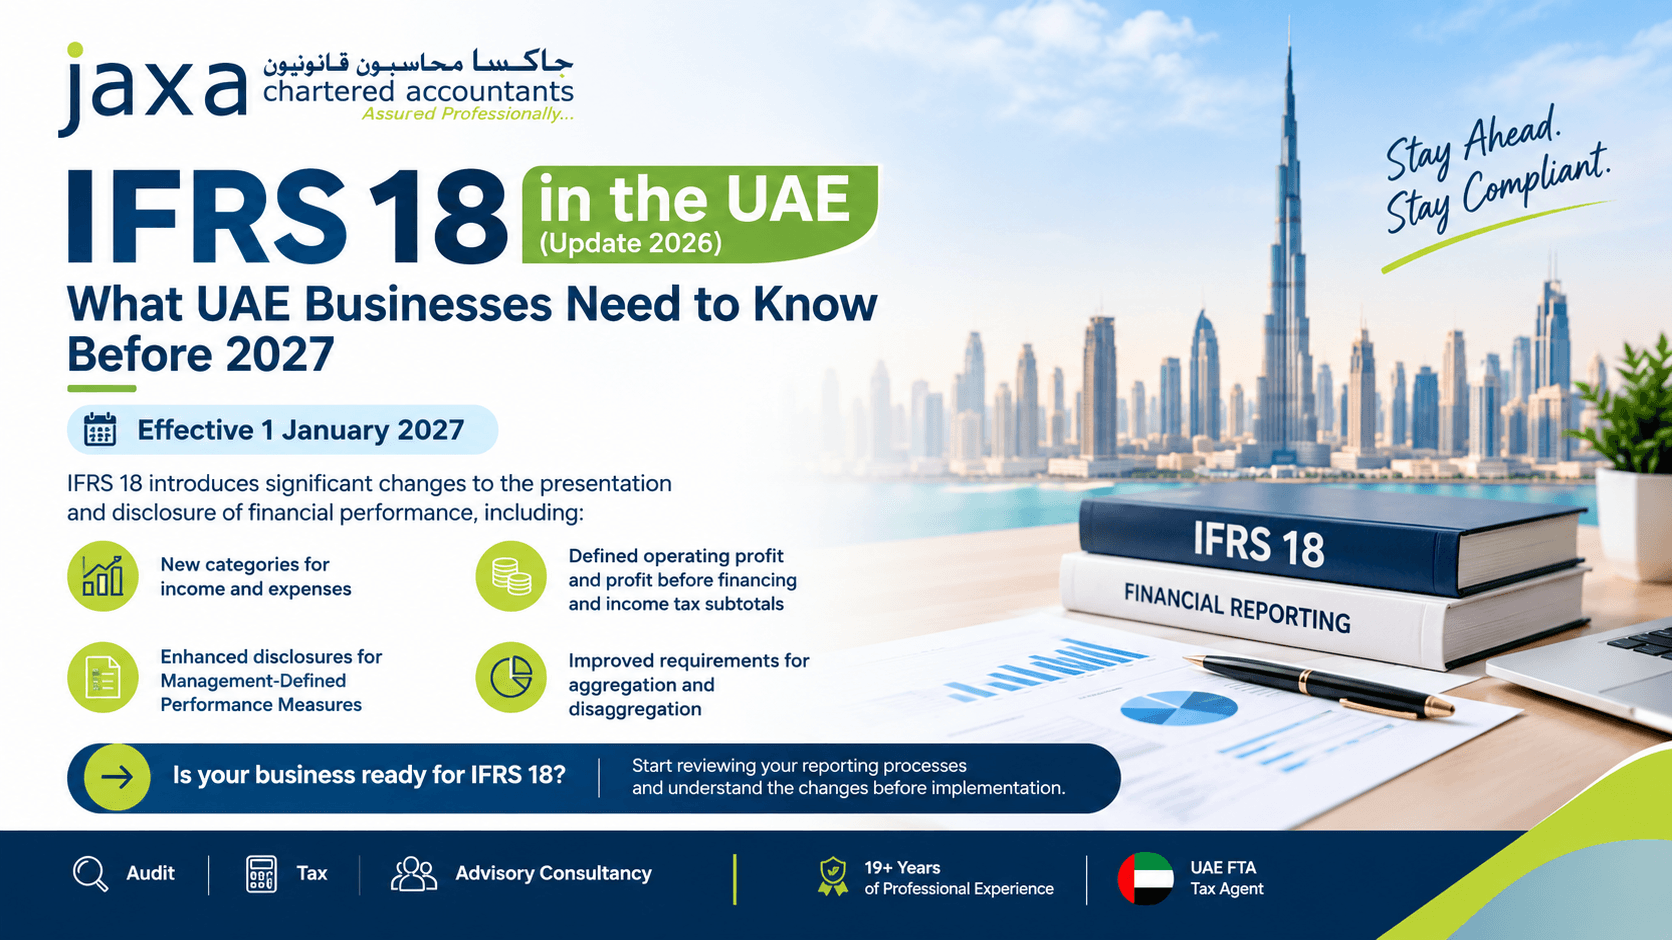
Effective for annual reporting periods beginning on or after January 1, 2027, IFRS 18 brings important changes to presentation and disclosure of financial information. These new requirements may affect most entities, making early preparation essential for businesses reporting under IFRS.
For UAE businesses, understanding these changes can help finance team assess their impact on financial reporting presentation, accounting system, disclosures requirements and internal controls, supporting a smoother transition to the new standard.
IFRS 18 in the UAE(Update): Key changes and implication for UAE businesses
IFRS 18- Presentation and Disclosure in Financial Statements introduces new requirements for financial statement presentation and disclosure, replacing IAS-1- Presentation of Financial Statements. Effective for annual reporting periods beginning on or after January 1, 2027, this standard aims to improve the transparency and comparability of financial performance.
For UAE businesses reporting under IFRS Accounting Standards, understanding the IFRS 18 requirements is an important step towards preparing for the upcoming changes. Businesses should review their existing financial reporting practices and identify areas that may require adjustments before implementation.
Key IFRS 18 changes business should know
- New categories and defined subtotals: IFRS 18 introduces defined categories in the Statement of profit or loss and requires companies to present specific subtotal, including:
- Operating profit or loss
- Profit or loss before financing and income taxes
These changes are intended to improve consistency and comparability between companies.
Businesses should review their existing profit and loss structure to understand how income and expenses may need to be classified under the new requirements.
- Management-defined Performance measures:
One of the important IFRS 18 requirements is the introduction of disclosure for Management-Defined Performance Measure (MPMs).
MPMs are subtotals of income and expenses that are specified by IFRS Accounting Standards but are used by management in public communication to communicate management’s view of financial performance. These measures are not specified by IFRS Accounting Standards.
Businesses should identify measures that meet the definition and provide the required disclosure, including reconciliation with most directly comparable IFRS-defined subtotals or other required measures.
- Improved aggregation and disaggregation
IFRS 18 also introduces enhanced principles for aggregation and disaggregation of financial information in financial statements.
Companies are required to aggregate items with similar characteristics and disaggregate items with different characteristics, ensuring that material information is clearly presented in the primary financial statements and accompanying notes.
These requirements may prompt entities to review their financial statement presentation, disclosure practice and reporting processes before IFRS 18 becomes effective for annual reporting periods beginning on or after January 1, 2027.
How will IFRS 18 Affect UAE businesses?
The impact of IFRS 18 will vary between businesses depending on their existing reporting structure and accounting practice.
Companies may need to review
- Financial statement presentation: Review the classification of income and expenses and presentation of required subtotals.
- Management Performance measures: Identify measures subject to the new disclosure requirements.
- Financial statement disclosure: Review aggregation, disaggregation and required disclosure.
- Accounting system and processes: Determine whether reporting system and data collection processes need updating.
- Internal control: Assess procedures for preparing and reviewing financial information
- Comparative information: Plan for retrospective application and the presentation of comparative figures.
For businesses in Dubai and across the UAE, an early IFRS 18 impact assessment can help identify implementation requirements ahead of the standard’s effective date of January 1, 2027.
How can businesses prepare for IFRS 18 in the UAE ?
With IFRS 18 in the UAE becoming effective January 1, 2027, businesses in Dubai and across the UAE should assess their financial reporting processes and prepare for the new presentation and disclosure requirements. Working with experienced accounting professionals in the UAE can help identify potential gaps and plan the transition.
- Review existing financial statements: review the current classification of income and expenses to identify changes required under IFRS 18. UAE companies IFRS financial statements should assess how the new categories and defined subtotals will affect their reporting.
- Assess management-defined performance measures: identify performance measures used in public communications and determine which falls within the new Management-defined Performance Measure(MPMs) disclosure requirements.
- Review accounting and ERP system: evaluate whether existing accounting software, ERP system, and reporting processes can capture the importation required for IFRS 18 compliance.
- Strengthen finance reporting controls: review accounting procedures and reporting controls to support consistent classification, aggregation, disaggregation and disclosure of financial information.
- Train finance and accounting team: Ensure finance professionals understand the new IFRS 18presentation and disclosure requirements
- Prepare comparative financial information: IFRS is applied retrospectively.
- Businesses should plan for the preparation of comparative financial information as part of their transition to the new standard.
IFRS 18 Implementation Timeline
| Period | Key Focus |
| 2026 | Assess the impact of IFRS 18 on existing financial statements and review reporting system, accounting policies and disclosure practices |
| Before first application | Prepare for retrospective application and comparative financial information. |
| January 1, 2027 | Effective date for annual reporting periods beginning on or after this date |
| First year of application | Apply IFRS 18 and provide the required restated comparative information and reconciliations. |
As IFRS 18 approaches its 2027 effective date, businesses across Dubai and the UAE should review their financial reporting practices and prepare for upcoming changes.
Get IFRS 18 Guidance in Dubai and Across the UAE
IFRS 18 introduces important changes to financial statement preparation and disclosure from 2027. Preparing for IFRS 18 requires a clear understanding of the applicable accounting standards and their impact on financial reporting. Jaxa Chartered Accountants provides professional audit, accounting and advisory services to businesses across the UAE.
With 19+ years of experience in Audit, Tax and Advisory Consultancy, jaxa Auditors supports businesses in reviewing financial reporting practices and addressing evolving accounting and regulatory requirements.
Professional financial reporting services in the UAE help businesses assess their current reporting practices, identify implementation gaps and plan the required changes. Businesses should seek accounting and audit services in Dubai can also obtain support in reviewing financial reporting processes and preparing for applicable accounting requirements.
If your business is preparing for IFRS 18, contact Jaxa Auditors in Dubai for professional guidance tailored to your reporting requirements.
Prepare for IFRS 18 before 2027
If your business is preparing IFRS financial statements, now is the time to assess the potential impact of IFRS 18.
Jaxa Chartered Accountants, a UAE FTA tax agent with professional accounting and audit support in the UAE.
Stay Ahead of IFRS changes with expert guidance.


 Reach us on WhatsApp
