
Explore UAE corporate tax updates for 2026 with Jaxa Chartered Accountants and understand FTA Decision No. 15 of 2026, including exemption eligibility, application procedures, filing deadline, and key compliance requirements for eligible entities.
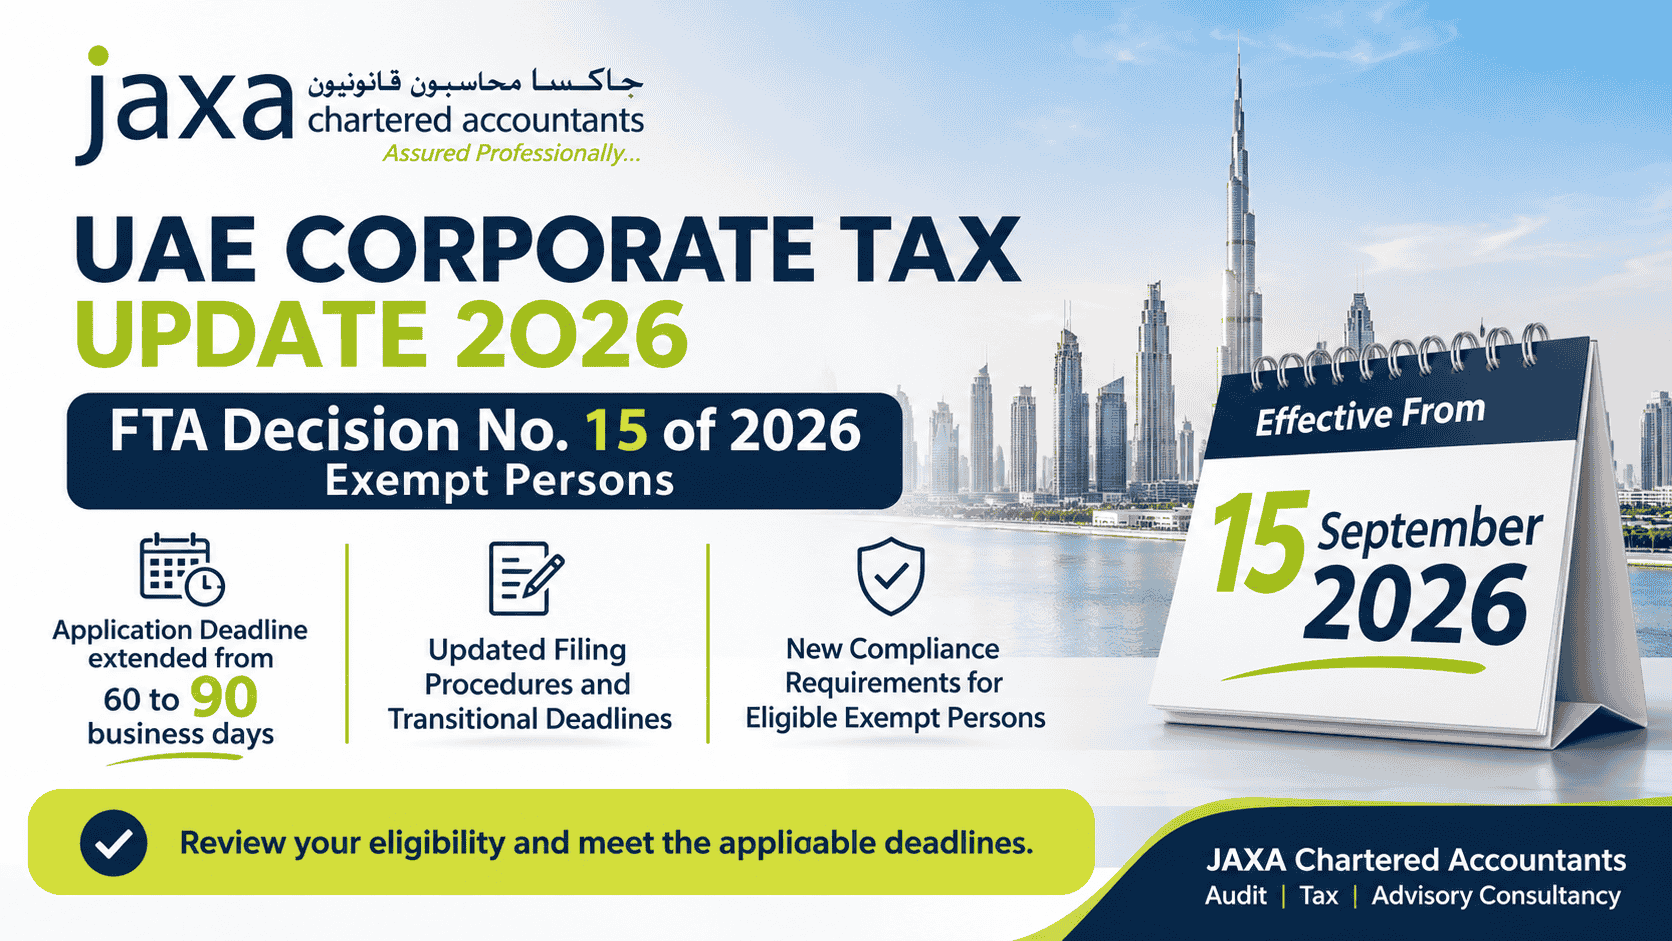
The UAE Federal Tax Authority (FTA) introduced Decision No. 15 of 2026, which highlights key changes to the procedures and deadlines governing UAE corporate tax exemptions, effective from September 15, 2026. This decision was issued on September 8, 2026. The updated provision specifies how revised procedures affect the UAE corporate tax exemption, including eligibility criteria, registration obligations, and submission deadlines.
The new decision replaces FTA Decision No. 7 of 2023 and revises the procedures applicable to certain categories of Exempt Persons under the UAE Corporate Tax Law. The eligibility conditions for Qualifying investment Funds, pension and social security funds and certain wholly owned entities continue to be governed by the UAE corporate tax law. The decision sets out the requirements to register for UAE corporate tax where applicable before submitting an exemption application through EmaraTax.
What does UAE FTA Decision No. 15 of 2026 mean?
According to UAE FTA Decision No. 15 of 2026, the amendment sets out the procedures for applying for corporate tax exemption for certain categories of entities under the UAE corporate tax framework established by Federal Decree- Law No. 47 of 2022, as amended.
The decision focuses on the application process and compliance requirements for relevant categories of Exempt Persons. It does not introduce new categories of exempt entities or replace the existing conditions under the UAE Corporate Tax Law.
Key areas covered by the Decision
- Exemption application procedures: Establishes the procedures for submitting corporate tax exemption applications for relevant categories of exempt persons.
The decision applies specific categories of Exempt Persons under Article 4(1) of the UAE Corporate Tax Law, including:
- Qualifying Public benefit entities
- Qualifying investment funds
- Qualifying limited partnerships
- Public and private pension or social security funds
- Certain wholly owned and controlled subsidiaries of eligible exempt persons
- Other person designated for exemption
It is important to note that UAE FTA Decision No. 15 of 2026 does not govern the exemption procedures for every type of entity. Government Entities and qualifying extractive businesses and non-extractive natural resource businesses fall under separate provisions of the UAE Corporate Tax Law.
Furthermore, exemption status should be assessed separately from compliance obligations. Eligible entities should review their registration requirements, application deadlines, documentation obligations, and record retention or other applicable statutory requirements.
Key changes introduced by UAE FTA Decision No. 15 of 2026
- UAE Corporate tax exemption application deadline extended to 90 business days
The revised decision of UAE FTA Decision No. 15 of 2026 specifies the standard timeframe for corporate tax exemption applications, allowing eligible entities to submit corporate tax applications within 90 Business Days following the end of the relevant tax period, replacing the previous 60 business day period
The eligible entities must submit the UAE corporate tax exemption application following the close of the relevant tax period in which they satisfy the exemption requirement. Weekends and official federal government holidays are excluded while calculating the deadline.
The extended timeframe allows eligible entities more time to verify their eligibility, assess their registration status, and prepare documentation within the applicable deadline.
Transitional provision and deadline under UAE FTA Decision No. 15 of 2026
Under FTA Decision No. 15 of 2026, specific categories of entities may be subject to transitional deadlines while applying for UAE corporate tax exemption covering previous tax periods. The deadline varies according to the applicable exemption provision and the periods covered by the application.
| Eligible entity | Catch-up deadline | Applicable period or application |
| UAE juridical persons wholly owned and controlled by a Government Entity or Government Controlled Entity, as specified under Article 3(5) | October 31, 2026 | Tax Period ending before January 1, 2026 providing the exemption conditions were met for the relevant periods. |
| Persons covered by Article 4(1)(i) who qualify for retrospective exemption under Cabinet Decision No. 55 of 2025 | December 31, 2026 | Retrospective exemption applications covered by the relevant provisions. |
| Juridical person eligible under Article 5 of Cabinet Decision No. 34 of 2025 | December 31, 2026 | Tax period that commenced in 2025 and ended on or before August |
With effect from September 15, 2026, UAE FTA Decision No. 15 of 2026 supersedes the previous exemption procedure under FTA Decision No. 7 of 2023. Its provisions apply to tax periods starting on or after June 1, 2023, provided relevant exemption applications are filed on or after September 15, 2026.
The revised decision specifies the procedures and deadline for corporate tax exemption applications but does not mention a new monetary threshold. The eligibility continues to depend on the conditions specified in the UAE Corporate Tax Law and Ministerial Cabinet Decision. Eligible entities should review these provisions before submitting a UAE corporate exemption application.
Which entities are covered by UAE FTA Decision No. 15 of 2026?
Under FTA Decision No. 15 of 2026, this amendment sets out registration and exemption application procedures for the following categories:
- Qualifying investment funds
- Public and private pension and social security funds
- UAE juridical persons wholly owned and controlled by eligible exempt persons, as specified under Article 4(1)(i), subject to the applicable exemption provisions.
Other persons specified by Cabinet Decision under Article 4(1)(i), subject to the applicable exemption provisions.
Before applying for UAE corporate tax exemption, the relevant entities should ensure that their corporate tax registration obligations have been met. Their eligibility will be assessed against the requirements set out in UAE corporate tax law and applicable Cabinet Decisions.
Additional Key Provision of UAE FTA Decision No. 15 of 2026
- Parent and subsidiary application: For a qualifying parent-subsidiary structure covered by the decision, the parent entity must submit its exemption application before the wholly owned subsidiary. The UAE FTA will consider the subsidiary ‘s application only after approving the parent’s exemption.
- Effective date of exemption: Once approved, the exemption generally takes effect from the beginning of the tax period specified in the application. The UAE FTA may determine a different effective date in certain circumstances under the decision.
- Coverage of earlier tax periods: The Decision covers tax periods starting on or after June 1, 2023, where exemption applications are submitted on or after September 15, 2026, subject to the applicable provisions.
- Application Preparation: Entities should review the relevant exemption conditions, verify corporate tax registration status and ensure that all required information and supporting documents are available before applying.
Get UAE corporate tax services from Jaxa Chartered Accountants
Jaxa Chartered Accountants, a UAE FTA tax agent as well as corporate tax consultants, guides businesses and eligible entities with UAE corporate tax compliance, exemption eligibility review, registration and application procedures. Speak to our tax agent in the UAE for guidance on the requirements applicable to your entity under UAE FTA Decision No. 15 of 2026.
Steps to prepare for the revised UAE corporate tax exemption requirements
Businesses seeking exemption under the UAE corporate tax framework should consider the following steps to prepare for the revised procedures under FTA Decision No. 15 of 2026.
- Confirm eligibility under the applicable provision: Review the entity’s ownership structure, legal status, activities, and other relevant criteria to determine whether it qualifies for exemption under the Corporate tax law.
- Verify corporate tax registration requirements: Check whether the entity is required to register for UAE corporate tax and ensure the required registration procedures and deadlines have been met.
- Review the applicable filing deadline: Verify the applicable exemption deadline, whether it is the standard 90-business day period or a transitional deadline. Entities covered by transitional provisions apply, ensuring that applications are submitted by October 31, 2026 or December 31, 2026, as applicable.
- Prepare required supporting documents: Collect the necessary supporting records, including incorporation documents, ownership details, financial statements, and other information required to meet the relevant exemption criteria.
- Plan group-level applications: For a qualifying parent-subsidiary structure, coordinate the application process to ensure that the parent’s exemption application is submitted and approved before the subsidiary can be decided.
- Seek professional advice where necessary: Consult a tax professional if the entity’s eligibility is unclear, the application involves previous tax periods or additional clarification is required regarding the relevant exemption provisions.
Best corporate tax services in the UAE
Understanding the requirements under UAE FTA Decision No. 15 of 2026 is essential for entities seeking exemption from UAE Corporate tax. Jaxa Chartered Accountants provides professional corporate tax advisory and compliance services to help eligible entities understand the applicable regulations, meet filing deadlines and prepare their exemption applications.
Our UAE corporate tax services include:
- UAE corporate tax registration
- UAE Corporate tax exemption application assistance
- UAE corporate tax deadline compliance
- Corporate tax return and filing in the UAE
- Corporate tax implementation in the UAE
- UAE corporate tax Health check
Need help with UAE corporate tax exemption?
If your business requires guidance on corporate tax exemption eligibility, corporate tax registration status, or the application process, Jaxa Chartered Accountants can help you understand the relevant requirements and navigate the compliance process.
Let Jaxa Auditors guide you through the UAE corporate tax exemption process, from eligibility assessment to application preparation and deadline compliance.
Stay compliant. Meet every tax Deadline with Confidence.
FAQ
- What is FTA Decision No. 15 of 2026?
As UAE FTA Decision No. 15 of 2026, it sets out Corporate tax registration and exemption application procedures for specified categories of persons under the UAE corporate tax law. It replaces UAE FTA Decision No. 7 of 2023 and took effect on September 15, 2026.
2. What is the UAE Corporate Tax exemption application deadline in 2026?
The standard deadline is 90 Business Days after the end of the relevant Tax Period in which the exemption conditions are met. Specific transitional deadlines of 31 October 2026 and 31 December 2026 apply to certain eligible entities.
3. Does FTA Decision No. 15 of 2026 introduce new Corporate Tax exemption categories?
No. The decision updates application procedures and deadlines. The underlying exemption criteria remain governed by the UAE Corporate Tax Law and the relevant Cabinet and Ministerial Decisions.
4. Does Corporate Tax registration need to be completed before applying for exemption?
Yes. Under the decision, the relevant exemption application may be submitted after the Federal Tax Authority approves the entity’s Corporate Tax registration, where the exemption application provisions apply.
5. Does FTA Decision No. 15 of 2026 apply to previous Tax Periods?
Yes. It applies to Tax Periods commencing on or after 1 June 2023, where the relevant application is submitted on or after 15 September 2026, subject to the decision’s provisions.
6. How Can JAXA Chartered Accountants Help with UAE Corporate Tax Exemption?
JAXA Chartered Accountants provides UAE Corporate Tax advisory and compliance services, including Corporate Tax exemption eligibility assessments, registration support, exemption application preparation and filing deadline reviews. Our team helps eligible entities understand FTA Decision No. 15 of 2026, review applicable exemption requirements and manage their UAE Corporate Tax compliance obligations.

 Reach us on WhatsApp
