
The UAE’s Domestic Minimum Top-Up Tax (DMTT) regime introduces additional obligations for Multinational Enterprise (MNE) groups adhering to prescribed revenue thresholds. This regime applies to qualifying MNE Groups meeting the consolidated revenue of EUR 750 million or more in at least two of the four fiscal years preceding the fiscal year.
According to the Article 13 of Cabinet Decision No. 142 of 2024, the FTA mandates entities falling within the DMTT framework to comply with the registration, deregistration, and related notifications established by the UAE FTA.
The Decision addresses the compliance obligations of multinational enterprise (MNE) groups operating in the UAE, including registration deadlines, deregistration requirements and notification procedures when an entity moves in or out of the scope of the Top-up Tax regime. The UAE Top-up tax rules apply to Fiscal years beginning on or after January 1, 2025.
This tax alert highlights the tax provisions businesses need to consider.
Entities Subject to UAE DMTT Registration Requirements
The UAE Domestic Minimum Top-up Tax (DMTT) applies to Constituent Entities of multinational enterprise (MNE) Groups that meet the Pillar Two revenue threshold. An MNE Group generally falls within the scope where its annual consolidated revenue is EUR 750 million or more in at least two of the four Fiscal years immediately preceding the tested Fiscal year.
However, meeting the UAE Pillar Two revenue threshold does not automatically mean that every UAE entity has the same DMTT registration obligations. Each entity’s classification and status under the UAE Top-Up Tax legislation must be assessed to determine its applicable compliance requirements.
Certain categories, including those that qualify as Excluded Entities and Investment Entities, may be subject to specific treatment under the DMTT registration rules.
Each MNE Group should review their UAE entity structure and determine which entities fall within the UAE DMTT registration requirements before proceeding with UAE FTA registration.
UAE DMTT registrations: Applicable Deadlines
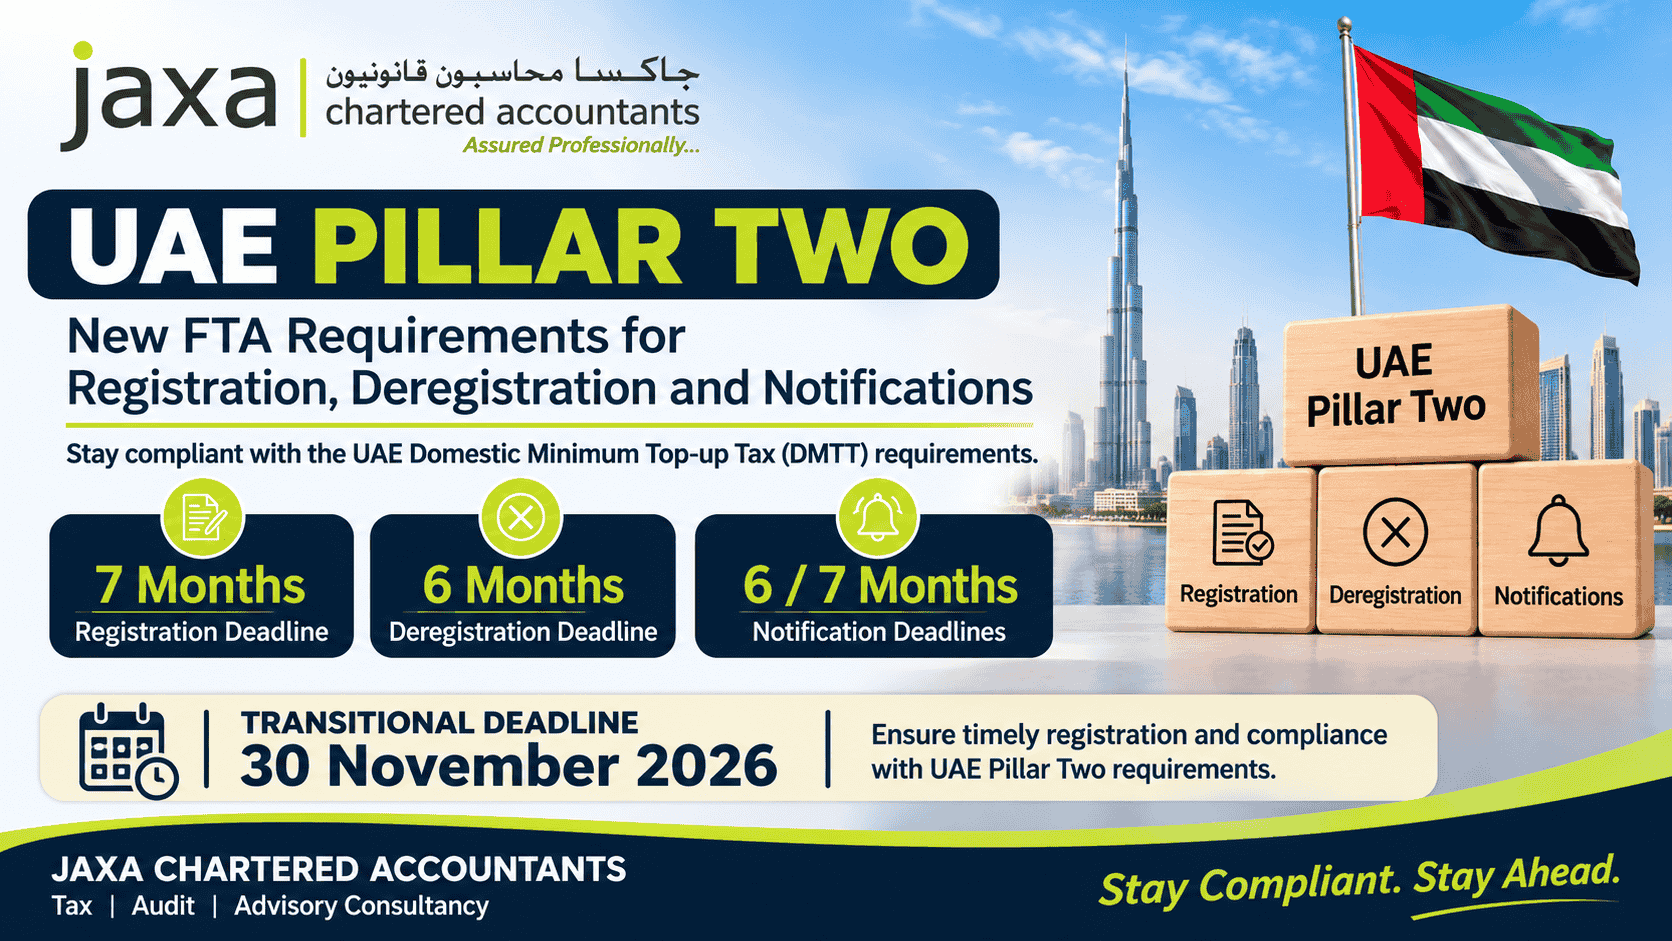
According to the Article 2 of FTA Decision No. 12 of 2026, an entity subject to the scope of the UAE Top-Up Tax must submit its DMTT registration application within seven months from the end of its first-in-scope Fiscal year.
The Decision highlights a transitional deadline for entities whose fiscal year ends before April 30, 2026. These entities must submit their DMTT registration application on or before November 30, 2026.
The applicable registration deadlines are detailed below:
| First-in-scope fiscal year end | Application timeline | Registration deadline |
| December 31, 2025 | Transitional | November 30, 2026 |
| June 30, 2026 | General | January 31, 2027 |
| December 31, 2026 | General | July 31, 2027 |
For instance, for entities with a first-in-scope fiscal year ending on December 31, 2026, the seven-month registration period results in an application deadline of July 31, 2027. However, entities whose fiscal year ends before April 30, 2026 must follow the transitional deadline rather than the general seven-month timeline.
Note: MNE Groups should assess their UAE Constituent Entities falling within the scope of the DMTT requirements and ensure that registration applications are submitted within the applicable deadlines, including the transitional deadline of November, 30, 2026 to ensure UAE FTA compliance.
Failure to fulfill registration within the prescribed period may result in non-compliance with the UAE FTA administrative requirements.
UAE DMTT Deregistration: Key Deadline
An entity that fails to fall within the UAE Domestic Minimum Top-Up (DMTT) framework must assess whether it needs to deregister with the UAE FTA.
Under Article 3 of UAE FTA Decision No. 12 of 2026, an entity must submit its deregistration application within six months from the earlier of the following dates:
- The date on which the entity ceases to exist; or
- The end of the fiscal year in which the entity exists as the MNE Group and ceases to fall within the scope of the DMTT law.
Transitional provision
For entities that cease to exist before June 30, 2026, the deregistration application must be submitted by December 31, 2026.
Additional Deregistration requirements:
The FTA Decision No. 12 of 2026 also specifies the following requirements applicable to the deregistration process:
- Settling outstanding obligations: Before deregistration, an entity must settle its outstanding Top-up tax and penalties and submit all due Top-up Tax returns and Pillar Two Information Returns.
- Validity of Tax Registration until Deregistration takes Effect
Upon approval of the deregistration application, the entity’s registration remains valid until the earliest of the following dates:
- The date on which the entity ceases to exist;
- The end of the fiscal year in which the entity leaves the MNE Group and ceases to fall within the scope of DMTT law; or
- Any other date determined by the UAE FTA.
- FTA’s Power to Initiate Deregistration
The FTA may, at its discretion, initiate deregistration of an entity where prescribed conditions for deregistration are met, even if the entity has submitted a deregistration application.
Jaxa’s Compliance Note: The applicability of the transitional registration deadline of December 31, 2026 appears to cover Entities that ceased to exist before June 30, 2026. Entities that existed as an MNE Group and became out of scope before this date, its deregistration obligation should be assessed independently. MNE Groups should review these situations to establish the appropriate compliance steps.
Registration and Tax return filing are separate Top-Up Obligations
Under the UAE Pillar Two framework, business must distinguish between three separate compliance obligations:
- Top-Up Tax registration
- Pillar Two Information Return
- Top-up Tax return and payment
The UAE FTA Decision No. 12 addresses the registration and deregistration framework. Therefore, the transitional deadline of November 30, 2026 should be considered specifically in the context of registration and not as a filing deadline for the first Top-up tax return.
Understanding the Transition between In-Scope and Out-of-Scope Status
According to Article 4 of FTA Decision No. 12, establishes the notification requirements and timelines for UAE Entities whose MNE Groups move into or out of the scope of the UAE DMTT regulations.
The key requirements are briefed below:
| Compliance Requirement | Applicable timeline |
| Out-of Scope Notification | Where an MNE Group ceases to be within the scope of the DMTT for a tested fiscal year, the Entity must notify the FTA within 6 months from the end of that fiscal year. |
| Validity of Out -of scope Notification | The notification remain valid for the tested fiscal year and the following 4 consecutive years, unless an in-scope notification becomes necessary |
| In-scope notification | If an entity with a valid out-of-scope notification becomes in scope again, it must notify the FTA within 7 months from the end of the tested fiscal year. |
| Deregistration after five consecutive out-of-scope fiscal years | If the out-of-scope notification remains valid for five consecutive fiscal years, the entity must apply for deregistration within 6 months from the end of the fifth fiscal year, unless an in-scope notification is required instead. |
Preparing for UAE DMTT Registration and Compliance
The UAE Federal Tax Authority has introduced DMTT registration through the EmaraTax portal, requiring MNE Groups to provide comprehensive details of their group structure, UAE Entities, Constituent members, and relevant supporting documentation and authorizations.
To facilitate the registration process and meet the prescribed deadlines, MNE Groups should prioritize the following steps
- Scope assessment: Identify all UAE Entities that fall within the scope of UAE DMTT.
- Group structure review: Evaluate changes in ownership, group composition and entity status during the relevant fiscal year.
- Registration strategy: Evaluate whether individual entity registration or registration through a domestic designated filing entity is more appropriate.
- Prepare supporting documentation: Ensure all relevant group-level and Entity-level information, supporting records and required authorizations are compiled to facilitate registration.
- Compliance management: Establish clear internal responsibilities, financial reporting procedures, clear accountability for DMTT reporting, tax return preparation, payment obligations and FTA communications.
Navigate UAE Pillar two requirements with confidence. Effective DMTT compliance requires careful planning, accurate registration, ongoing reporting and tax compliance. Jaxa Chartered Accountants, a UAE FTA-registered tax agent, assists businesses with professional tax advisory and compliance services to help MNE Group to manage their UAE DMTT registration, reporting and filing responsibilities.
UAE DMTT Compliance: Key Actions for MNE Groups
MNE Groups operating in the UAE should:
- Verify whether consolidated group revenue meets the EUR 750 million threshold in at least two of the preceding four fiscal year
- Identify all UAE Constituent entities
- Assess which entities fall within the scope of UAE DMTT.
- Review applicable exclusion and special entity classifications
- Determine the first in-scope fiscal year
- Clarify the applicable UAE FTA registration deadline
- Assign responsibility for registration, reporting, tax return filing and payment
- Keep a centralized compliance calendar.
Need professional guidance?
Jaxa Auditors, a UAE FTA tax agent provides Pillar Two tax advisory and compliance support to help businesses navigate UAE DMTT requirements.
Strengthen Your UAE Pillar Two Tax compliance Strategy with Professional tax agent in the UAE
The introduction of OECD’s Pillar Two framework in the UAE marks a significant development in the UAE corporate tax landscape. With the Domestic Minimum Top-Up(DMTT) now applicable to qualifying multinational (MNE)groups, businesses should understand their registration, deregistration, reporting and tax payment obligations.
With the transitional DMTT registration deadline of November 30, 2026 approaching, early preparation is a key to ensure timely DMTT registration planning, accurate entity identification and compliance readiness are within the prescribed timeframe.
Our corporate tax services in the UAE include
- UAE Corporate tax registration and deregistration
- UAE Corporate tax return filing
- UAE Corporate tax compliance and advisory
- UAE Compliance tax impact assessment
- UAE Transfer pricing compliance
- Free zone corporate tax advisory
- UAE FTA correspondence and tax audit support
- UAE Tax group registration and management
With 19+ years of professional experience, Jaxa Chartered Accountants is a UAE FTA tax agent providing corporate tax, VAT, and Pillar two advisory services. Our expertise covers DMTT scope assessment, entity mapping, Top-up registration, compliance planning and ongoing tax advisory.
Leverage Jaxa’s tax expertise to navigate UAE tax regulations, manage compliance risk and meet your regulatory obligations with confidence.
Prepare today. Stay complaint tomorrow
Do not wait for deadlines. Get Your UAE TAx compliance ready with Jaxa,
Visit our jaxaauditors.com for more updates


 Reach us on WhatsApp
